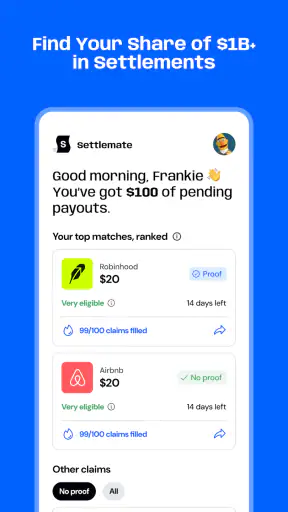
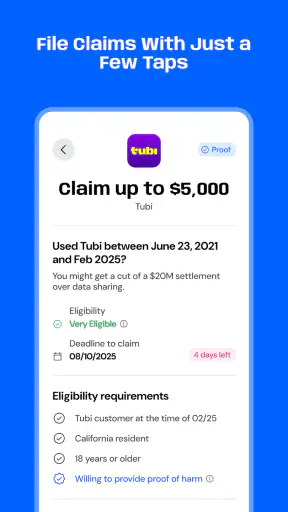
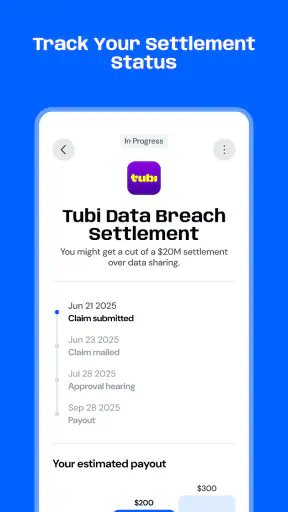
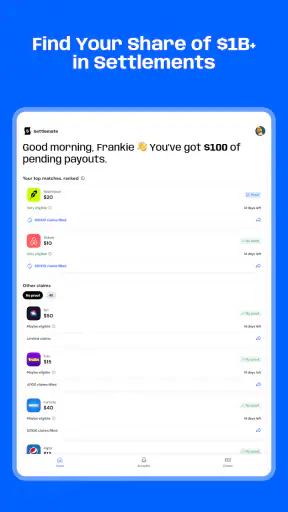
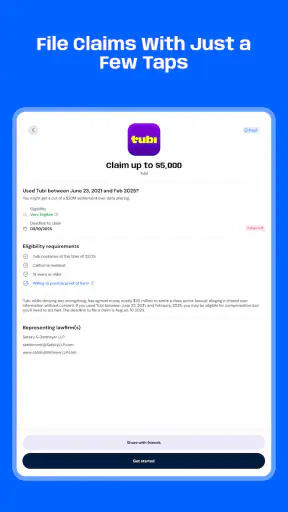
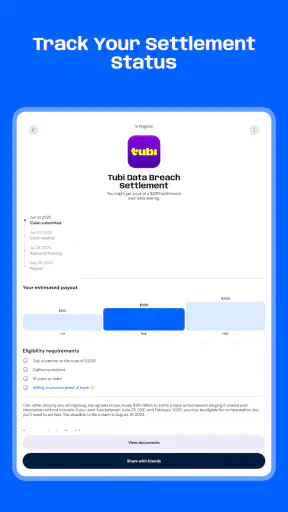
Settlemate is a finance app built around a simple but useful question: when a company owes you money, how do you keep track of it and move toward getting paid? I found its focus refreshingly narrow. Instead of trying to be a complete banking app, it gives attention to money that is due to you, which can otherwise disappear into old emails, forgotten forms, or a vague promise from a business.
That focus makes it especially interesting for people who regularly deal with refunds, reimbursements, compensation claims, delayed payments, or other amounts owed by companies. The app is free to download, with optional in-app purchases ranging from $1.99 to $64.99 per item. Settlemate is developed by Settlemate, belongs to the Finance category, and is suitable for Everyone. It runs on Android 8.0 and later, with version 4.5.1 available at the time of my review.
My overall impression is that Settlemate works best as a follow-up system rather than a magic money finder. It cannot replace careful documentation, a clear request, or patience when a company is slow to respond. What it can do is make the process more deliberate. If you have ever thought, “I need to chase that refund,” and then remembered it weeks later, that is the kind of problem this app is trying to solve.
How I would use Settlemate from the first claim to the final payment
The most practical way to approach the app is to treat every unpaid amount as a small project. I would begin by recording who owes the money, why it is owed, how much I expect, and what action needs to happen next. The important habit is not simply entering a claim; it is creating a clear record that can be revisited without reconstructing the whole story from memory.
A realistic example is a cancelled service that should result in a refund. I might first gather the cancellation email, the original receipt, and any reference number. Then I would create the relevant entry in Settlemate, write a short description in plain language, and note the date of my request. That gives me a starting point for follow-up instead of relying on a flagged email that may later get buried.
I would also keep the wording consistent. A useful note might say that the service was cancelled, the refund was requested, and the company has not yet confirmed payment. Short, factual notes are more valuable than an emotional diary because they help me understand the next step quickly. If the company replies, I can update the record with the response and avoid sending a duplicate message or making an unnecessary complaint.
This is where the app feels different from a normal notes app. A notes app can store the information, but it does not naturally encourage me to think in terms of an amount owed and a follow-up routine. A spreadsheet offers more control, but it takes more effort to design and maintain. Settlemate sits between those options: more focused than general notes, but less demanding than building a personal tracking system from scratch.
I would not use it as my only evidence. The original invoice, cancellation confirmation, screenshots, and correspondence should remain available in their original locations. Settlemate is better treated as the control panel for the situation. It helps me remember what happened and what I should do next, while the supporting documents prove the claim if the company asks for details.
The small setup decisions that make the record useful
The quality of the result depends heavily on the information I enter. I would avoid vague titles such as “money issue” and use something specific, like “refund for cancelled annual subscription.” That makes a list of several open matters much easier to scan. I would also include the company name in the main description rather than assuming I will remember it later.
Another helpful habit is separating the amount expected from the amount actually received. A partial payment should not be treated as a completed case. If a company refunds only part of a charge, the remaining balance deserves its own follow-up. This distinction matters because a quick glance at a bank account can make a payment look complete when it is not.
I found that dates are useful even when they are approximate. The date of the original charge, the date of the request, and the date of the latest reply tell me how long the issue has been active. They also prevent a common mistake: contacting a company again without remembering that I sent a message only yesterday.
For shared household finances, I would add the person responsible for the next action in the note. For example, one person may have the receipt while another has the customer-service conversation. Settlemate is more effective when the entry explains who needs to do what, rather than simply announcing that money is missing.
Settings worth checking before relying on the app
I would spend a few minutes reviewing the app’s available settings before creating a large collection of entries. In a finance tool, small choices about reminders, display preferences, notifications, and account behavior can affect whether I actually return to the app. The best setup is the one that supports a repeatable routine without creating so many alerts that I start ignoring them.
Notifications deserve particular attention. A reminder is useful when it points to a real action, such as checking whether a refund arrived or sending a follow-up message. It becomes noise when every minor change produces an interruption. I prefer fewer, meaningful prompts and would adjust them around my own schedule rather than accepting a constant stream of alerts.
I would also check how the app handles completed items and whether they remain easy to review. A paid claim should not clutter the active list, but it can be useful to retain a history for future reference. If a company disputes a later charge or I need to check a previous refund, a clean archive is more valuable than deleting everything as soon as the money arrives.
Because this is a finance app, I would pay attention to privacy-related choices in the settings and be selective about what I enter. I would record the details needed to identify the claim, but I would avoid placing unnecessary card numbers, passwords, or sensitive identity information into ordinary notes. The app can help organize a claim without becoming a storage place for every confidential document connected to it.
I would also review the purchase area before assuming every useful function is included at no cost. Settlemate is free to use at its basic entry point, but optional purchases are available, with individual items priced from $1.99 to $64.99. I would look at what a purchase unlocks, whether it solves a problem I actually have, and whether the same result can be achieved through a simpler manual habit.
That last point is important for occasional users. Someone tracking one refund may not need to pay for advanced convenience. A person managing many claims, reimbursements, or recurring follow-ups may value a paid option more, but I would still test the free workflow first. A purchase should reduce a real source of friction, not merely make the app feel more complete.
Faster patterns for people who track several claims
Experienced use of Settlemate is less about entering more information and more about entering the same useful information every time. I would create a personal template in my notes outside the app, then use that structure whenever I add an item: company, reason, amount, request date, reference number, last contact, and next action. This keeps records comparable and makes a busy list easier to manage.
I would process new claims in one short session instead of adding them randomly throughout the day. For example, after checking email or household accounts, I could enter every new amount owed, attach the relevant context in the description, and decide which items need attention first. That batching habit reduces the chance that one small refund will be forgotten simply because it arrived at an inconvenient time.
Prioritization is another useful pattern. I would put time-sensitive matters first, followed by larger amounts, then low-value claims that can wait. A delayed reimbursement needed for a bill is more urgent than a minor overcharge from a company that has already acknowledged the issue. Settlemate can hold the list, but I still need to apply judgment to it.
I would use a three-stage rhythm: capture, follow up, close. Capture means recording the claim while the details are fresh. Follow up means checking the company’s response and updating the record after each meaningful contact. Close means confirming the money has arrived and marking the matter finished. Keeping these stages separate prevents the common error of considering a claim solved just because an email was sent.
For recurring situations, I would avoid copying old entries without reviewing every detail. A previous refund request may contain an outdated amount, old contact information, or a different deadline. Reusing a structure is efficient; blindly reusing facts is risky. The app helps with consistency, but it cannot know whether the new case truly matches the old one.
One of the less obvious benefits is emotional. Chasing money can feel disproportionately tiring when each case is small. A visible list turns that vague irritation into a set of manageable actions. I can see which matter needs a message, which one is waiting on a company, and which one is finished. That clarity makes it easier to act without repeatedly revisiting the whole problem.
Where Settlemate is stronger than ordinary alternatives
Compared with a banking app, Settlemate has a different purpose. A bank can show that money arrived, but it usually does not explain why I am waiting for a payment or what conversation led to it. Settlemate is useful before the transaction appears, when the problem is follow-up rather than balance checking.
Compared with email flags, it provides a more deliberate place to collect separate claims. Email is still essential for communication, but a flagged message can become invisible among newsletters, receipts, and unrelated conversations. A dedicated entry lets me summarize the situation and track the next action without opening several message threads.
Compared with a spreadsheet, the advantage is reduced setup. A spreadsheet can be excellent for detailed calculations, household budgets, or large-scale reporting. If I need formulas, custom dashboards, or extensive sorting, I would choose the spreadsheet. Settlemate makes more sense when I want a focused workflow for money owed and do not want to design the system myself.
Compared with a general task manager, the finance-specific purpose is its main benefit. A task such as “contact company” does not automatically preserve the amount, reason, or payment status. Settlemate keeps the financial context close to the follow-up. That makes it more suitable for claims where the money and the action are inseparable.
There is a trade-off, though. A narrowly focused app may not replace tools I already use for budgeting, document storage, or communication. I would not expect Settlemate to become my complete financial command center. Its value comes from doing one job clearly, not from absorbing every financial task.
Advanced limits and the situations where I would skip it
Settlemate cannot force a company to pay. If a business rejects a claim, ignores repeated requests, or requires a formal dispute process, the app can organize my information but cannot resolve the disagreement. I would still need to understand the company’s terms, contact the appropriate support channel, or use a consumer-protection or payment-dispute process when appropriate.
I would also be cautious about using it for complicated accounting. A business owner who needs invoices, tax treatment, reconciliation, or accounts-receivable reporting would probably be better served by dedicated accounting software. Settlemate’s appeal is personal clarity around money owed, not professional bookkeeping.
It may also be unnecessary for someone who rarely has an outstanding claim. If I receive one refund every few years and already have a reliable email reminder habit, installing another app could create more maintenance than value. The strongest case is for people with several open matters or a repeated pattern of reimbursements and refunds.
Another limitation is that organization still depends on discipline. If I fail to update an entry after a company replies, the record becomes stale. If I enter incomplete amounts or forget to mark partial payments, the list can give me false confidence. The app reduces memory work, but it does not remove the need for accurate input.
I would be especially careful when several people are involved. A household may need a shared source of truth, and an individual tracking app may not be enough if everyone needs simultaneous access or formal accountability. In that situation, a shared spreadsheet or collaborative task system could be the better choice, even if it takes longer to configure.
Finally, I would not confuse a clean interface with legal proof. The strongest claim remains the one supported by receipts, agreements, and correspondence. Settlemate can help me find those materials and remember the timeline, but I would preserve the originals and avoid relying on a summary alone in a serious dispute.
Who will get the most from the app
I think Settlemate is a good fit for people who regularly pay for subscriptions, travel, services, or purchases and occasionally need to recover money from companies. It is also useful for employees waiting for reimbursements, families managing several refunds, and anyone who tends to postpone follow-up because each individual amount feels too small to prioritize.
The app is less compelling for people seeking investment tools, spending analysis, bill payment, or a full household budget. Its purpose is not to tell me where all my money goes. It is about the money that should come back or arrive from someone else. That distinction is worth understanding before downloading it.
The audience size suggests that the idea has found real interest: Settlemate has passed 500,000 installs, with an average rating of 4.3 from around 38,000 ratings and roughly 2,200 written reviews. Those figures do not change my personal assessment, but they do show that the problem is familiar to many users rather than being an overly niche concern.
Its Everyone age rating also makes the app approachable for a broad audience, although younger users should still be thoughtful about entering personal financial details and should involve a trusted adult when handling a serious dispute. The simple concept is accessible, but the consequences of a claim can still be significant.
My verdict after building a repeatable habit
Settlemate is most useful when it becomes a calm follow-up habit, not another place to dump forgotten tasks. I would open it after finding a refund or reimbursement issue, record the facts while they are fresh, set a realistic next action, and return after each response. That routine turns an uncertain promise into something I can actively manage.
I like the app’s narrow purpose and the way it fills the gap between a banking app, an email inbox, and a spreadsheet. The free starting point makes it easy to test, while the optional purchases mean I would inspect the available upgrades rather than buying automatically. Version 4.5.1 is the current version I reviewed, and the Android requirement of 8.0 or later keeps it accessible on older supported devices.
My recommendation is strongest for anyone who has several companies owing them money at the same time or who repeatedly forgets to chase small claims. I would skip it if I need full accounting, complex collaboration, or a tool that can resolve disputes on my behalf. For the right user, though, Settlemate offers something genuinely practical: a dedicated place to turn “they owe me” into a documented, repeatable path toward getting paid.


